Fresh Tomato Wholesale Prices and Supply Trends November 2026
A structural delay in the Mediterranean tomato harvest has triggered a supply gap across Europe. Discover how current Almería auction peaks are impacting wholesale procurement in the Nordics and Benelux.
Market note
Get the latest fresh tomato wholesale prices for Northern Europe. Navigate the current Almería supply shortage and secure volume for Germany and Benelux.
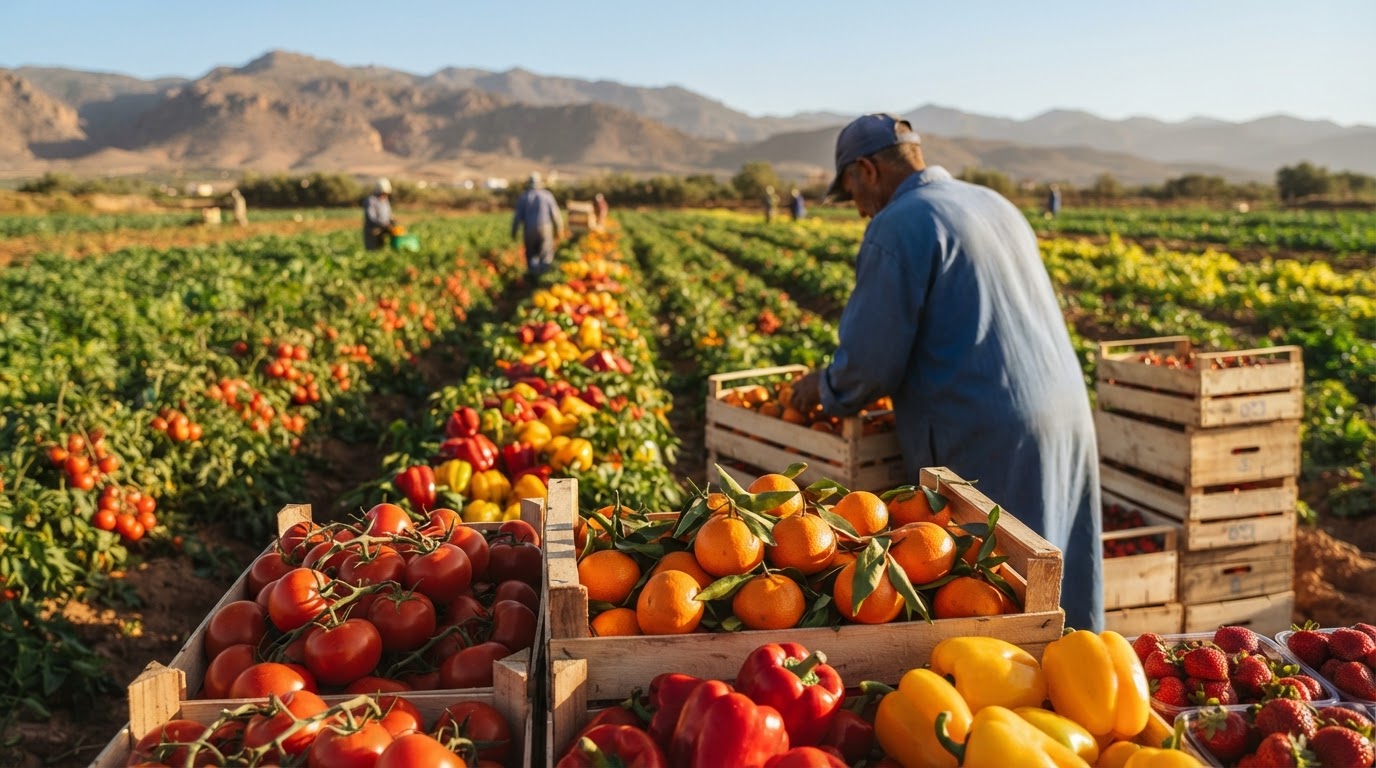
As of November 3, 2026, fresh tomato wholesale prices across Northern Europe are facing significant upward pressure due to a synchronized production delay in the primary Mediterranean growing hubs. For buyers in the Netherlands, Germany, Belgium, and the Nordics, the transition from local summer greenhouse cycles to winter imports has hit a structural bottleneck. High thermal variability at the tail end of the summer and aggressive pest management strategies in Almería have resulted in a notable lack of ripened fruit ready for the export lanes to Rotterdam and Frankfurt.
Why are fresh tomato wholesale prices rising this week?
The current market volatility is rooted in a deliberate shift in planting schedules. Following heavy viral pressure from insect vectors earlier this year, many growers in the Andalusian region postponed their transplanting phases to avoid the peak heat of late summer. This strategic delay was intended to safeguard crop health, but it has created a void in week 44 and 45 availability. Consequently, auction houses are seeing intense competition for limited volumes as Northern European summer crops have completely finished, leaving retail programs undersupplied.
Current market pricing for plum and vine tomatoes
Pricing data from the southern Spanish auctions indicates that values have climbed well above the three-year seasonal average. For procurement managers in the Benelux and German markets, these floor prices at the source dictate a high-entry cost for the month of November. The current benchmarks for first-grade fruit are as follows:
- Plum tomatoes: Averaging €2.06 per kilo at source.
- Vine tomatoes: Reaching highs of €2.50 per kilo for premium grades.
- Daniela (Round) tomatoes: Trading between €1.73 and €2.20 per kilo.
- Supply gap duration: Full production volumes are not expected until mid-November.
- Import competition: Moroccan production is also trailing 10 to 15 days behind schedule.
When will tomato supply normalize for Northern European buyers?
Historical trends usually see significant volumes flooding the Agadir and Almería export corridors by late October. However, 2026 is proving to be an outlier. Trade experts suggest that the industry should not expect a stabilization of volume until the second or third week of November. This 14-day lag is particularly critical for foodservice providers in the Nordics, who rely on consistent weekly arrivals to maintain fixed-price menus. With Morocco also facing a delayed start, there is a looming risk of a 'supply peak overlap' later in the month, which could lead to sudden price corrections after this period of scarcity.
“The delay in transplanting greenhouse crops is likely becoming a structural norm rather than a one-off seasonal event, fundamentally changing how we forecast autumn supply chains.”
Sourcing consequences for German and Dutch wholesalers
For wholesalers in Rotterdam and Hamburg, the immediate consequence is a focus on 'quality over volume.' With prices for vine tomatoes approaching the €2.50 mark before logistics costs are even applied, buyers are being forced to tighten specifications to ensure that every kilo landed justifies the premium. The delayed ripening has also affected size distribution; early harvests are leaning toward smaller calibers, making large-sized plum tomatoes exceptionally rare and expensive in the current market.
Strategic procurement: How to manage the mid-November gap
We advise our partners in the Nordics and Germany to move away from spot-market reliance during this window. As Almería cooperatives like Vicasol—which handles nearly 90,000 tons annually—report that peak production is still weeks away, securing volume through established import programs is the only way to avoid the volatility of the daily auctions. Buyers should also prepare for the possibility that Moroccan acreage reductions may further tighten the market if the Spanish harvest does not accelerate rapidly.
Logistics and transit considerations for the Nordics
The transit lane from the Mediterranean to the Northern frontiers is currently seeing high demand for refrigerated capacity despite the lower fruit volumes. Because the available product is being harvested under variable thermal conditions, maintaining the cold chain from the packing house to the final destination in Scandinavia is paramount. Crown Fields continues to monitor these transit times closely to ensure that the delayed fruit maintains its shelf life upon arrival in Rotterdam for onward distribution.
To navigate this period of record-high auction prices and secure your tomato programs for the remainder of Q4, contact the Crown Fields trade desk. We provide our partners with real-time pricing updates and direct access to premium Mediterranean greenhouse harvests.
Frequently asked
Buyer questions we get on this topic
- Why are tomato prices so high in the Netherlands and Germany right now?
- Prices are elevated because the Spanish and Moroccan seasons are delayed by roughly two weeks. Producers postponed planting to avoid summer heat and pests, leading to a gap where summer greenhouse production in Northern Europe has ended but winter import volumes haven't yet reached their peak. This scarcity at the auction level is driving plum tomato prices above €2.00 per kilo.
- When will the tomato shortage in Europe end?
- Market analysts expect supply to stabilize by mid-November 2026. While Spain typically reaches full export volume by late October, this year's delay means the market won't see significant relief until the second or third week of November. Buyers should expect high volatility and tight specifications until at least week 46.
- Is the current tomato supply gap a one-time event?
- Industry experts suggest this delay in transplanting may become a permanent shift in the agricultural calendar. By delaying the season, growers can better manage pest pressure and extreme heat, but it results in a structural supply gap every autumn for Northern European buyers who depend on the transition from local to imported produce.